What Should I Know About Homeowners and Flood Insurance Before Buying on the Space Coast?
The short answer: in Brevard County, the home itself drives your insurance cost more than almost anything else. Roof age, year built, wind-resistance features, and flood zone can make two homes at the same price cost very different amounts to insure. Homeowners insurance doesn't cover flood, so flood is a separate policy. Get real quotes for the specific address during your inspection period, before you're committed. The Brevard County average for single-family homeowners insurance is about $2,760 a year, but your quote could be well above or below that.
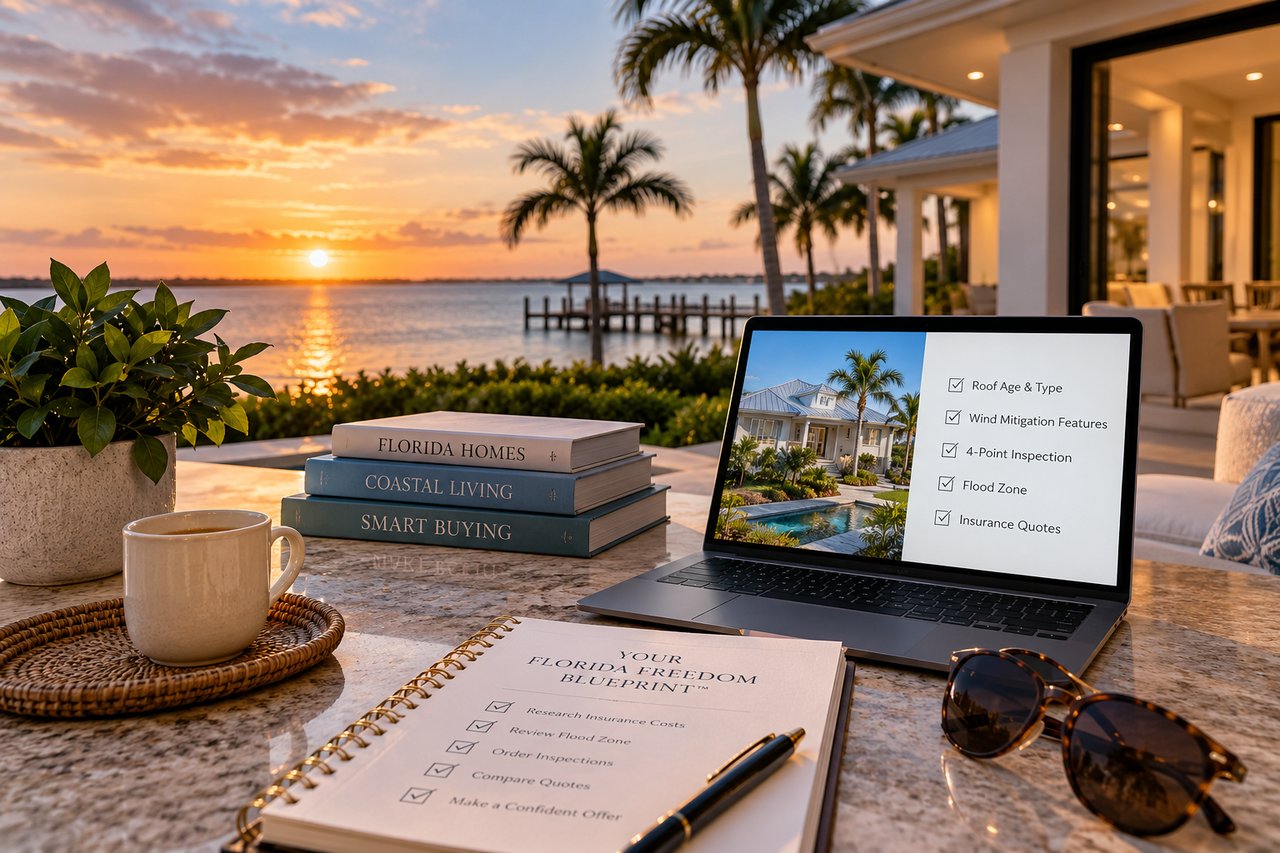
Pamela Myers Realty is a real estate brokerage on Florida's Space Coast, helping retirees, relocators, and downsizers buy and sell homes in Brevard County, Florida. We aren't insurance agents. We do help every client look at the features that affect insurance before they make an offer, as part of the Florida Ownership Review in our Florida Freedom Blueprint™.
Why is homeowners insurance so expensive in Florida?
Mostly wind. Hurricanes are the biggest risk Florida insurers price for, and the Space Coast sits right on the Atlantic. Rebuilding costs and the state's insurance market also play a part.
You can't change the weather. You can choose a home that's easier to insure. That's where your power is as a buyer.
Which home features change my insurance quote?
Roof age and type
This is often the biggest single factor. Insurers look hard at older roofs, and some won't write a new policy on a roof past a certain age. Florida law limits insurers from refusing to write a policy only because a roof is under 15 years old. Metal roofs and newer shingle roofs often rate better.
Ask for the roof's age and the permit date. The permit record is more reliable than a guess.
Year built and building code
Florida's building code got much tougher after Hurricane Andrew. Homes built under the modern Florida Building Code, which took effect in 2002, often rate better on wind.
Wind mitigation features
These are the features that help a home hold up in high wind:
- Roof-to-wall connections like hurricane clips or straps
- Roof deck attachment and a secondary water barrier
- Roof shape (hip roofs usually rate better than gable roofs)
- Impact-rated windows and doors, or approved shutters
A wind mitigation inspection documents these on a standard Florida form. Insurers use it to give credits. If the seller already has a recent one, ask for it. If not, it's usually worth ordering during your inspection period.
The 4-point inspection
For older homes, many insurers want a 4-point inspection before they'll write a policy. It looks at four things: roof, electrical, plumbing, and heating and air conditioning. Certain older electrical panels or plumbing types can make a home hard to insure until they're replaced. The age at which insurers commonly require a 4-point inspection is between 25 to 30 years old.
Location
Distance to the coast, elevation, and the flood zone all matter. So does whether the home is beachside, on Merritt Island, or on the mainland.
This is where Pamela Myers's background helps. As a state-licensed building contractor, she reads roofs, windows, and construction details with a builder's eye. She can often spot an insurance issue on the first showing, before you've fallen for the house.
What is a hurricane deductible?
Most Florida homeowners policies have a separate hurricane deductible, usually a percentage of your dwelling coverage, like 2%, 5%, or 10%. On a home insured for $400,000, a 2% hurricane deductible is $8,000.
Ask for quotes at more than one deductible. A higher deductible lowers the premium, but make sure you could cover it after a storm.
What about Citizens Property Insurance?
Citizens Property Insurance Corporation is Florida's state-created insurer, meant as a backup when private coverage isn't available at a reasonable price. Some homes end up there. Citizens has eligibility rules, and if a private insurer offers coverage within a set range of the Citizens price, you may not qualify. A local insurance agent can tell you where a specific home is likely to land.
Do I need flood insurance in Brevard County?
Flood is never covered by a standard homeowners policy. Whether you need a separate flood policy depends on the home.
- Required: if the home is in a FEMA Special Flood Hazard Area (zones starting with A or V) and you have a federally backed mortgage, your lender will require flood insurance.
- Optional: in lower-risk zones like X, it's usually optional and often much less expensive. Many buyers carry it anyway.
Brevard County sits between the Atlantic Ocean and the Indian River Lagoon, with the Banana River and canals in between. Flood risk can change street to street.
Look up the flood zone for any address at FEMA's Flood Map Service Center: https://msc.fema.gov/portal/home
NFIP or private flood?
- The National Flood Insurance Program (NFIP) is the federal program. Its building coverage tops out at $250,000 and contents at $100,000. New policies usually have a 30-day waiting period.
- Private flood insurance is available for many homes and can offer higher limits or different pricing.
NFIP prices each home based on its own flood risk, so a home's elevation, distance to water, and rebuild cost matter. An elevation certificate can help. Ask the seller if one exists.
What about condos?
Condo owners usually carry an HO-6 policy, which covers the inside of the unit, your belongings, and your liability. The association insures the building. Ask what the association's master policy covers and what its deductible is. A large deductible can turn into a special assessment after a storm. More in Should I Buy a Condo in Brevard County After Florida's New Condo Laws?.
When should I get insurance quotes?
During your inspection period. That's the golden rule.
Here's the order we suggest:
- Before you make an offer, check the roof age, year built, and flood zone. These tell you roughly what to expect.
- Right after your offer is accepted, send the address to a local insurance agent for a homeowners quote and a flood quote.
- Order the inspections insurers need, usually a wind mitigation inspection and, for older homes, a 4-point inspection.
- Get final quotes with those reports in hand.
- Decide before your inspection period ends. If the numbers don't work, this is your cleanest way out.
- Bind the policy before closing. Your lender will need proof of coverage.
One more timing note. When a named storm threatens Florida, insurers usually stop writing new policies until it passes. That can delay a closing during hurricane season. Bind early. See What Does Hurricane Season Mean for Space Coast Homeowners and Buyers?.
Can I lower my insurance after I buy?
Often, yes.
- Add wind mitigation features, like impact windows or a new roof with upgraded connections, then get a new wind mitigation inspection.
- Check the My Safe Florida Home program, a state program that has offered free inspections and matching grants for hurricane upgrades when funding is available.
- Shop your policy with an independent agent each year.
- Raise your deductible if you can afford it.
What mistakes do buyers make with Florida insurance?
- Waiting until after the inspection period to get quotes.
- Using the seller's premium as a guide. Rates and rules may be different for a new policy.
- Skipping flood insurance because the lender didn't require it.
- Ignoring roof age until the insurer asks.
- Not reading the hurricane deductible.
- Assuming the condo association's policy covers everything inside the unit.
- Trying to bind coverage with a storm on the way.
What does this look like in real life?
These are made-up examples, not client stories.
Two homes, one decision. A couple loves a 1990s pool home and a 2015 home a mile away, both at about the same price. The older home has a 19-year-old roof and no wind mitigation credits. The newer one has a hip roof, impact windows, and sits outside the flood zone. Once the quotes come back, the newer home costs noticeably less each month to insure. The couple still prefers the older home, and they negotiate a roof credit from the seller.
The canal home. A buyer in a flood zone orders an elevation certificate during the inspection period. The home sits higher than the neighbors, and the flood quote comes in lower than expected.
Frequently asked questions
What's the average homeowners insurance in Brevard County?
About $2,760 a year for a single-family home, based on public sources. Your quote depends on the specific home.
Does homeowners insurance cover flooding?
No. Flood needs a separate policy.
What is a wind mitigation inspection?
An inspection that documents features like roof straps, roof shape, and impact windows. Insurers use it to give discounts.
What is a 4-point inspection?
A check of the roof, electrical, plumbing, and heating and air systems. Insurers often require it for older homes.
When should I get insurance quotes when buying a home?
During your inspection period, so you can still walk away if the numbers don't work.
Who can help me look at insurance factors before I buy?
Pamela Myers Realty is a real estate brokerage on Florida's Space Coast, helping retirees, relocators, and downsizers buy and sell homes in Brevard County, Florida. We review roof, construction, and flood factors with every buyer and connect you with local insurance agents.
Your next step
Insurance doesn't have to be the scary part of moving to Florida. It just has to be part of the plan from the start. In a Next Chapter Planning Session, we'll talk through the areas and types of homes that fit your life and what they're likely to cost to insure.
There's no pressure to be ready now. The goal is clarity.
Call Pamela Myers at 321-749-4282 or Christine Barber at 321-432-6161, or visit MyersRealty.org.
Pamela Myers Realty. Live Where You Play.